Central Banks | 3 min read | June 2026

What's on the Horizon for the Global Economy?

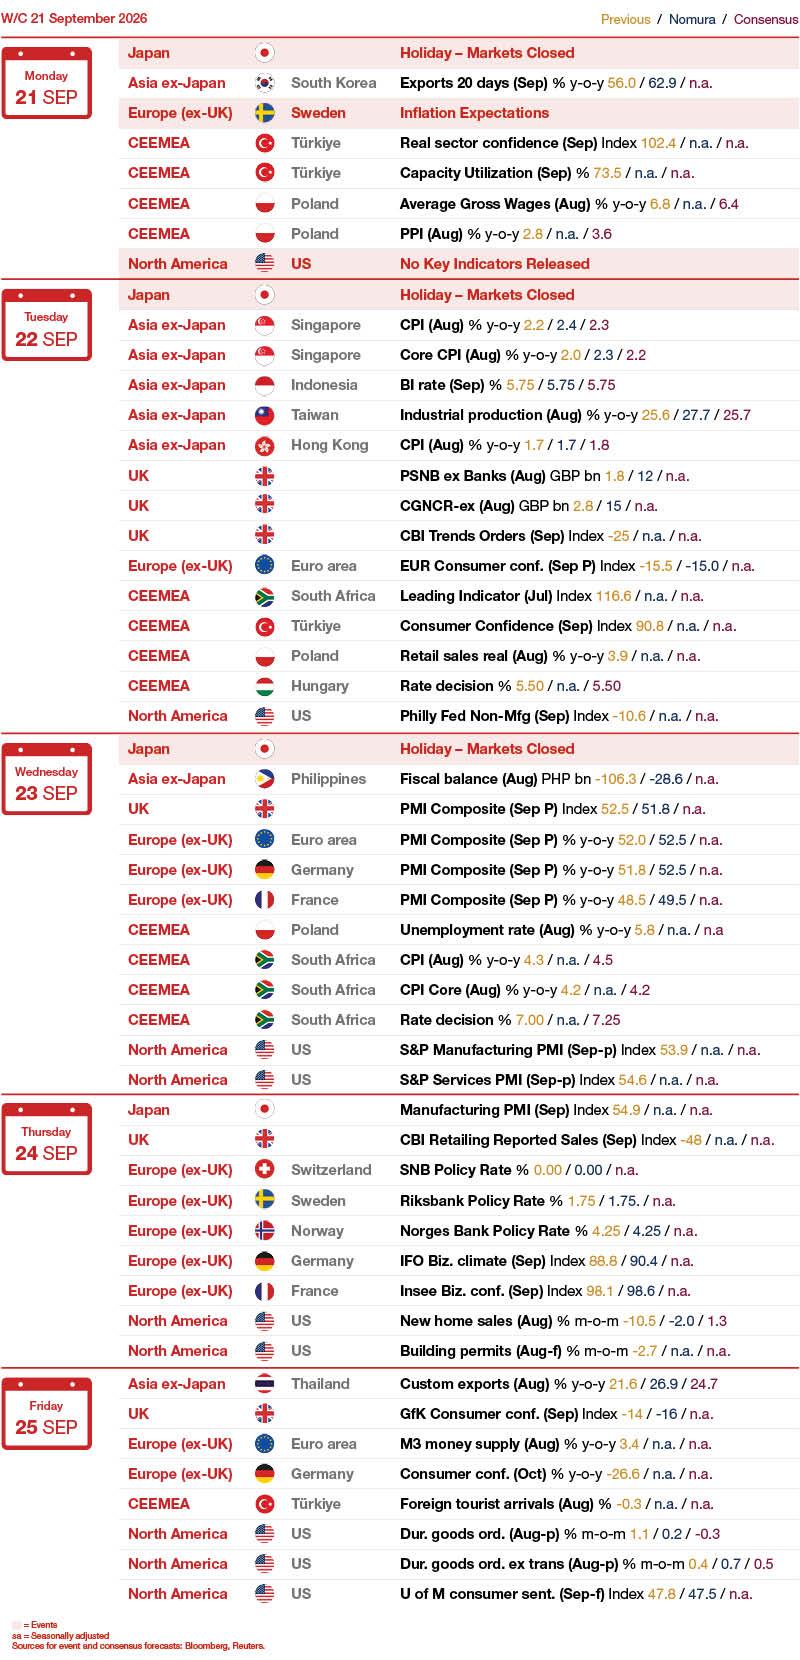
Our weekly updated overview highlights the key releases of global economic market data from around the globe and provides an economic outlook for 2026 by region.

Aichi Amemiya

Senior US Economist

George Buckley

Chief UK & Euro Area Economist

Ting Lu

Chief China Economist

Kyohei Morita

Chief Economist, Japan

Euben Paracuelles

Week Ahead Podcast Host and Chief ASEAN Economist

David Seif

Chief Economist for Developed Markets

Rob Subbaraman

Head of Global Macro Research

Sonal Varma

Chief Economist, India and Asia ex-Japan

  • Our Week Ahead podcast explores the key themes driving global markets next week
  • Our Global Economic Markets Data Calendar shows upcoming events happening over the week
  • We provide an outlook overview region by region
Global Markets Data Calendar

Our view in a nutshell

Japan

  • We expect rate hikes in September 2026, and January and April 2027. A weaker JPY could lead to four hikes.
  • Near-term rate hike(s) will be driven by risks rather than the BOJ’s main scenario of the economy and prices
  • The government has decided to cut the VAT rate for food from 8% to 1% for two years starting in April 2027.
  • We expect capex to drive recovery though GDP-based real capex has been subdued for the last five quarters.

China

  • The current status of the economy could be best described as a big divergence and domestic weakness.
  • We expect Beijing to initiate a new round of supportive measures. However, in our view, the scale of such measures might be limited.
  • Considering ample market liquidity and falling CGB yields, we maintain our forecast for no RRR and rate cuts until Q2 next year.
  • We expect the ongoing AI boom to widen both demographic and geographic inequality, which could further dent demand.

Rest of Asia

  • Sustained AI demand and a gradual normalization of the energy supply chain bode well for Asia’s economic outlook.
  • We expect Taiwan, Malaysia and Singapore to outperform, and we remain cautious on Indonesia and Thailand.
  • Elevated oil prices, El Niño, and rising memory prices pose upside risks to inflation.
  • Most Asian central banks have turned hawkish, amid better-than-expected growth and rising inflation.
  • Korea: We expect two more 25bp rate hikes as the BOK expects strong growth and demand-side inflation (terminal rate: 3.50%).
  • India: With a faster rise in food and oil prices, and firming core inflation momentum, we forecast two 25bp RBI hikes in Q4.
  • Singapore: Spillovers from the tech boom and strong domestic demand should boost growth and lift core inflation to above 2.0%. 
  • Australia: We think a 25bp rate hike on 29 September is more likely than not, and see risk of a more pronounced macro cycle.
  • New Zealand: We expect growth to recover and forecast one more 25bp hike in December, to return policy to roughly neutral.

United States

  • We now expect the Fed to deliver a 25bp hike at the September meeting.
  • This is likely to be followed by another hike in December.
  • Little inflation progress and a sharp rise in energy prices led us to revise our call.
  • Growth is likely to remain strong due robust fixed investment and steady personal consumption.
  • The labor market has stabilized, and we expect the unemployment rate to decline.

Canada

  • We expect the BoC to hold rates steady, with risks skewed to tightening.
  • Labor markets have shown some signs of stabilization, but risks remain skewed to the downside.
  • Falling rents and slowing wage growth are likely to offset elevated energy prices, keeping underlying price pressures contained.

Euro Area

  • Growth was resilient in H1 2026, though headwinds from the Iran war remain for H2 2026. We see growth improving into 2027.
  • We expect inflation to print above target in the quarterly profile until early 2027, due to the conflict in Iran. 
  • We expect two more ECB rate hikes in December 2026, and March 2027, lifting the depo rate by to 3.00%. 
  • We expect a meaningful fiscal loosening in Germany this year, but there are risks it is offset by fiscal tightening elsewhere.

United Kingdom

  • Due to the conflict in Iran, we have revised up our forecast and expect inflation rise and peak at around 3.5% this year.
  • GDP growth was strong at 0.6% and 0.4% q-o-q in Q1/Q2, respectively, but there are questions over ONS seasonal adjustments.
  • Downside risks: weaker job market, elevated saving ratio. Upside risks: sticky services inflation, Middle East conflict.
  • We expect a BoE to leave rates unchanged for the rest of 2026, and to see two rate cuts in H2 2027.

Scandinavia and Switzerland

  • Switzerland: Inflation has accelerated, but core inflation remains low. We see no change in rates for the foreseeable future.
  • Sweden: Inflation is low but has surprised us to the upside recently. GDP growth was strong in Q2. We expect a March 2027 hike.
  • Norway: Norges Bank raised rates in May to counter sticky inflation, we expect another 25bp rise in November and a cut in 2027. 

CEEMEA

  • Türkiye: Under the new economic program, inflation continues to decrease despite some delays in meeting interim targets.
  • Türkiye: Due to resilient growth and upside risks to inflation, the CBRT maintains its hawkish stance to anchor expectations.

For more information read our weekly report here.
 

Contributors

Aichi Amemiya

Senior US Economist

George Buckley

Chief UK & Euro Area Economist

Ting Lu

Chief China Economist

Kyohei Morita

Chief Economist, Japan

Euben Paracuelles

Week Ahead Podcast Host and Chief ASEAN Economist

David Seif

Chief Economist for Developed Markets

Rob Subbaraman

Head of Global Macro Research

Sonal Varma

Chief Economist, India and Asia ex-Japan

Disclaimer

This content has been prepared by Nomura solely for information purposes, and is not an offer to buy or sell or provide (as the case may be) or a solicitation of an offer to buy or sell or enter into any agreement with respect to any security, product, service (including but not limited to investment advisory services) or investment. The opinions expressed in the content do not constitute investment advice and independent advice should be sought where appropriate.The content contains general information only and does not take into account the individual objectives, financial situation or needs of a person. All information, opinions and estimates expressed in the content are current as of the date of publication, are subject to change without notice, and may become outdated over time. To the extent that any materials or investment services on or referred to in the content are construed to be regulated activities under the local laws of any jurisdiction and are made available to persons resident in such jurisdiction, they shall only be made available through appropriately licenced Nomura entities in that jurisdiction or otherwise through Nomura entities that are exempt from applicable licensing and regulatory requirements in that jurisdiction. For more information please go to https://www.nomuraholdings.com/policy/terms.html.